Market overview of the Pet Intravenous (IV) Fluid Supplies Market
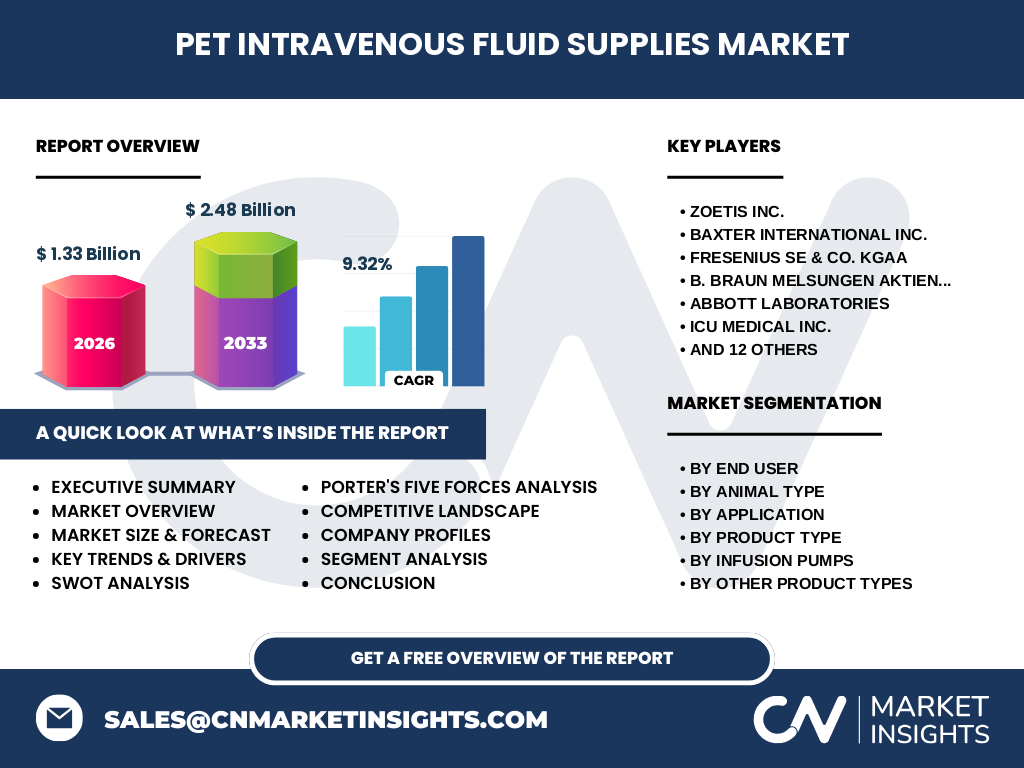
The Pet Intravenous (IV) Fluid Supplies Market encompasses critical medical consumables required for fluid resuscitation, perioperative support, and critical care in veterinary medicine. Valued at $1.33 Billion in 2026, this sector is essential for managing trauma, dehydration, and surgical procedures across companion and livestock animals, underpinned by stringent aseptic manufacturing standards overseen by regulatory agencies like the FDA and EMA.
Structural Growth Drivers and Market Restraints
Our analysis indicates that rising pet humanization and advanced veterinary diagnostics are primary catalysts. Conversely, the Pet Intravenous (IV) Fluid Supplies Market industry trends reveal supply chain vulnerabilities regarding medical-grade PVC and phthalate-free plasticizers. Strict sterilization protocols and cold-chain logistics hurdles further constrain rapid manufacturing scaling for key players such as Baxter International Inc. and B. Braun Melsungen Aktiengesellschaft.
Emerging trends and growth patterns in the sector
The shift toward home-based chronic disease management has accelerated demand for ambulatory infusion pumps and specialized catheter securement devices. Technological integration in veterinary hospitals, such as smart volumetric infusion pumps from companies like Moog Inc., enhances dosing precision and minimizes iatrogenic fluid overload in feline and canine patients.
COVID-19 impact analysis and recovery trajectory
The pandemic caused severe disruptions in raw material procurement and port congestion for finished fluid bags. However, the post-pandemic recovery trajectory shows robust rebound, driven by accelerated pet adoption rates and expanded veterinary clinic investments in emergency care infrastructure, cementing a lucrative path toward future valuations.
Competitive Benchmarking and Strategic Dynamics
The competitive landscape features a blend of human healthcare giants and specialized animal health leaders. Firms like Zoetis Inc., Fresenius SE & Co. KGaA, and Terumo Corporation leverage extensive global distribution networks. Strategic mergers and proprietary needleless connector innovations serve as primary moats to defend market share against aggressive generic manufacturers.
Executive summary of key findings
Our comprehensive report reveals a thriving sector projected to reach $2.48 Billion by 2033, expanding at a notable 9.32% CAGR from 2027 to 2033. High-growth segments like crystalloid fluid bags and veterinary hospitals and clinics dominate revenue streams, offering lucrative entry points for investors navigating regulatory and logistical complexities.
Market forecast from 2027 to 2033
Driven by rising disposable incomes and advanced veterinary surgical offerings, the Pet Intravenous (IV) Fluid Supplies Market market size is slated for stellar expansion. Growing from its 2026 baseline, the market will scale aggressively through 2033, heavily influenced by surging demand in emergency care and specialized oncology infusions for geriatric pets.
Segmentation analysis across product, animal, and end-user categories
Segmentation spans multiple critical axes: Product Type (Intravenous Fluid Bags, Administration Sets, Catheters, Infusion Pumps); Animal Type (Dogs, Cats, Horses, Other); Application (Emergency Care, Surgery, Chronic Disease); and End User (Veterinary Hospitals, Animal Research Institutes, Home Care). Each segment addresses specialized clinical needs, from over-the-needle catheters to complex parenteral nutrition bags.
Regional market analysis and geographic distribution
North America commands the largest revenue share due to high pet insurance penetration and sophisticated veterinary infrastructure. Meanwhile, the Asia-Pacific region exhibits the fastest growth trajectory, propelled by rising urbanization, expanding disposable incomes, and an increasing number of corporate-backed veterinary hospital chains in emerging economies.
In-depth regional review of key markets
In North America, strict USP pharmacopeia standards dictate manufacturing compliance for firms like Abbott Laboratories and ICU Medical Inc. European markets focus on sustainable, phthalate-free infusion sets, whereas Asia-Pacific regional growth is heavily concentrated in urban veterinary hubs across Japan and China, requiring localized regulatory navigation.
Company profiles and strategic positioning
Key market participants such as Covetrus Inc., Henry Schein Inc., and Dechra Pharmaceuticals PLC dominate through vast distribution channels and bundled product offerings. Specialty players like Mila International Inc. and Jorgensen Laboratories Inc. focus on niche veterinary catheter accessories, securing strong brand loyalty among clinical practitioners.
Porter's Five Forces analysis of the industry
Bargaining power of suppliers is moderate due to specialized medical-grade polymer requirements. Threat of substitutes remains low given the clinical necessity of IV administration. However, competitive rivalry is intense among established conglomerates like Vetoquinol S.A., Norbrook Laboratories Limited, and B. Braun Melsungen Aktiengesellschaft, squeezing operating margins.
SWOT analysis of the Pet Intravenous (IV) Fluid Supplies Market
Strengths include robust product efficacy and established clinical protocols. Weaknesses involve high sensitivity to polymer resin price volatility. Opportunities lie in emerging pet care markets and home-care infusion solutions. Threats encompass stringent FDA/EMA compliance audits and potential disruptions in global shipping lanes.
Value chain analysis from raw materials to end-users
The value chain originates with petrochemical refiners supplying medical-grade PVC and silicone, followed by specialized compounders. Tier-1 manufacturers like Baxter International Inc. and Fresenius SE & Co. KGaA execute aseptic blow-fill-seal molding. Distribution occurs via veterinary wholesalers like Covetrus Inc. before reaching end-user clinics.
Investment insights and strategic recommendations
High-potential areas include eco-friendly, PVC-free infusion bags and smart ambulatory pumps for home care settings. Investors should prioritize partnerships with established veterinary distributors like Henry Schein Inc. to mitigate market entry barriers and capitalize on high-margin specialty segments.
Conclusion and key takeaways for stakeholders
The Pet Intravenous (IV) Fluid Supplies Market industry trends confirm robust, recession-resistant demand anchored by companion animal healthcare expenditure. Stakeholders must embrace product innovation—such as needleless connectors and advanced fluid warmers—to capture market share in this fast-evolving, high-margin veterinary landscape.
Research methodology and data triangulation
Our baseline estimates are rigorously triangulated by combining customs trade registry data, primary qualitative interviews with veterinary surgeons and procurement officers, and secondary macroeconomic indicators. This multi-tiered approach ensures high fidelity in sizing niche segments like syringe infusion pumps and parenteral nutrition bags.
Scope of the report and coverage parameters
This report covers global revenue performance, volume shipments, and strategic shifts across veterinary hospitals, research institutes, and home care settings from 2026 to 2033. Excluded from this scope are human-exclusive critical care formulations not commonly cross-labeled or utilized in veterinary clinical practice.
Recent developments, partnerships, and strategic moves
Recent industry momentum highlights strategic acquisitions by giants like Zoetis Inc. and collaborative distribution pacts involving regional players such as Aromor Animal Health Private Limited and Sykes Veterinary International Limited. These moves aim to optimize supply chain resilience and expand geographic footprints in underserved veterinary markets.